Free Download Portfolio Management using Machine Learning: Hierarchical Risk Parity – Includes Verified Content:
Portfolio Management using Machine Learning: Hierarchical Risk Parity – Watch this Video Sample for Free
Portfolio Management using Machine Learning: Hierarchical Risk Parity – Watch this PDF Sample for Free
Portfolio Management using Machine Learning: Hierarchical Risk Parity – Watch the Content Proof for Free
Portfolio Management using Machine Learning: Hierarchical Risk Parity
Managing a portfolio effectively requires more than intuition—it demands a systematic, data-driven approach. Traditional portfolio allocation techniques like equal-weighted portfolios (EWP), inverse volatility portfolios (IVP), and the Markowitz critical line algorithm (CLA) each have their strengths and weaknesses. However, in today’s volatile financial markets, these methods often fall short of delivering robust, risk-adjusted performance.
That’s where Hierarchical Risk Parity (HRP) comes in. In the course Portfolio Management using Machine Learning: Hierarchical Risk Parity, offered by QuantInsti, learners are guided step by step in applying HRP to a real-world set of 16 stocks. This approach leverages concepts from machine learning, hierarchical clustering, and risk management to create more balanced, resilient portfolios.
Why Hierarchical Risk Parity Matters
Hierarchical Risk Parity is a cutting-edge portfolio allocation method that overcomes several limitations of traditional approaches:
-
EWP assumes all assets should carry equal weight, ignoring volatility differences.
-
IVP improves balance but struggles with correlation and clustering effects.
-
CLA, rooted in mean-variance optimization, can be overly sensitive to estimation errors.
By contrast, HRP organizes assets into a hierarchical structure using clustering algorithms and dendrograms, then allocates weights in a way that minimizes risk concentration. This results in portfolios that are both diversified and more robust to market shocks.
What You’ll Learn in This Course
The course blends theory, coding, and real-world application to ensure learners not only understand the concepts but also gain hands-on experience.
Key learning outcomes include:
-
Portfolio allocation with HRP: Apply the method to real stock data and compare results with IVP, EWP, and CLA.
-
Stock screening techniques: Build a stock screener to filter assets before allocation.
-
Backtesting strategies: Test and compare portfolio performance across methods using historical data.
-
Hierarchical clustering: Implement algorithms, understand the mathematics, and visualize clusters.
-
Dendrogram interpretation: Learn how to read linkage matrices and cluster visualizations.
-
Risk and performance analysis: Calculate returns, volatility, and drawdowns to evaluate strategies.
By the end of the program, learners will have a Python-based framework for building and testing advanced portfolio strategies.
Skills Covered
This is not just a finance course—it’s a hands-on data science and machine learning training for trading. Learners will work extensively with:
-
Programming & Libraries: Python, NumPy, Pandas, Sklearn, Matplotlib, Seaborn.
-
Portfolio Management: IVP, CLA, HRP, return/risk optimization.
-
Mathematics & ML Concepts: Hierarchical clustering, linkage matrices, dendrograms, Euclidean distance, scaling methods.
These skills are directly applicable to quantitative finance, algorithmic trading, and risk management roles.
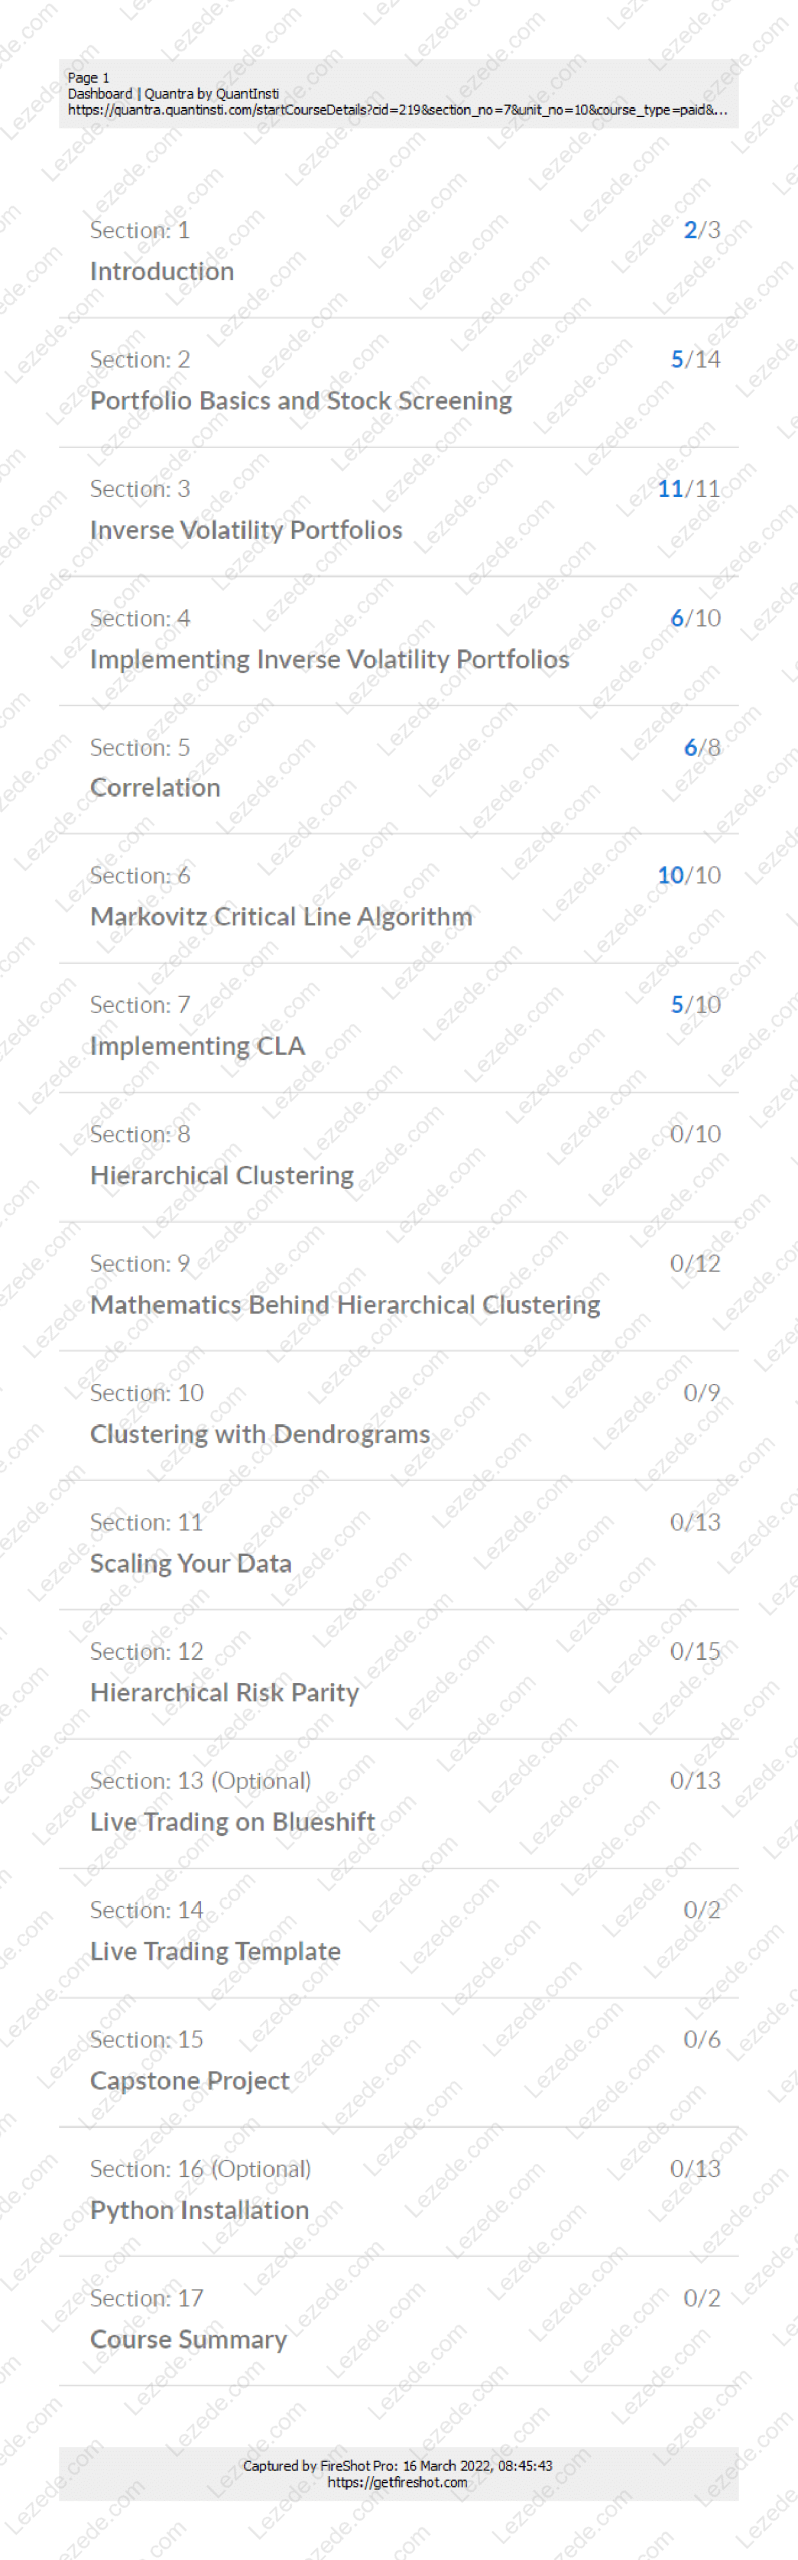
Course Syllabus Overview
-
Introduction – Course structure and objectives.
-
Portfolio Basics & Stock Screening – Foundations of portfolio management.
-
Inverse Volatility Portfolios (IVP) – Theory and implementation.
-
Correlation Analysis – Measuring asset relationships.
-
Markowitz Critical Line Algorithm (CLA) – Classic optimization method.
-
Hierarchical Clustering – Concepts, mathematics, and coding.
-
Clustering with Dendrograms – Visualization and interpretation.
-
Scaling Data – Preparing datasets for clustering.
-
Hierarchical Risk Parity (HRP) – Full implementation and analysis.
-
Backtesting & Performance Evaluation – Comparing HRP with IVP, EWP, and CLA.
-
Live Trading on Blueshift – Applying strategies in a trading environment.
-
Capstone Project – End-to-end portfolio management task.
Who Should Take This Course?
This course is designed for:
-
Intermediate traders and investors who want to upgrade from traditional allocation methods.
-
Quantitative analysts and data scientists looking to apply machine learning to finance.
-
Portfolio managers aiming to strengthen risk management frameworks.
-
Aspiring algorithmic traders interested in hands-on Python implementations.
Prerequisites: A general understanding of financial markets, basic knowledge of Pandas and Matplotlib, and familiarity with Python programming.
About the Instructor – QuantInsti
Founded by the creators of iRage, one of India’s top high-frequency trading firms, QuantInsti is a global leader in algorithmic and quantitative trading education. With users across 190+ countries, QuantInsti has been shaping the future of trading education for over a decade through its research-driven learning ecosystem.
Final Thoughts
The financial markets are evolving, and so should your portfolio management strategies. With the Hierarchical Risk Parity approach, traders and investors can achieve smarter, more stable diversification that traditional models often fail to deliver.
By combining machine learning, risk parity, and Python-driven implementation, this course gives you a toolkit for robust capital allocation in today’s unpredictable markets.
If your goal is to balance risk and reward more effectively, the Portfolio Management using Machine Learning: Hierarchical Risk Parity course is an essential step forward.