Free Download Deep Reinforcement Learning in Trading By Dr. Thomas Starke – Includes Verified Content:
Deep Reinforcement Learning in Trading By Dr. Thomas Starke – Watch this Video Sample for Free
Deep Reinforcement Learning in Trading By Dr. Thomas Starke – Watch this PDF Sample for Free
Deep Reinforcement Learning in Trading By Dr. Thomas Starke – Watch the Content Proof for Free
Deep Reinforcement Learning in Trading By Dr. Thomas Starke
Financial markets are dynamic, uncertain, and full of delayed rewards—exactly the kind of environment where Reinforcement Learning (RL) shines. Unlike traditional machine learning, which often works with static input-output pairs, RL learns by interacting with the market, making decisions (actions), observing the outcomes (rewards), and improving strategies over time.
The course Deep Reinforcement Learning in Trading by Dr. Thomas Starke takes you on a journey from the foundations of RL to advanced trading applications, equipping you with the skills to design, train, and deploy RL models in real-world trading environments.
Why Reinforcement Learning for Trading?
Trading is inherently a delayed gratification problem. A position you enter today might only yield profits—or losses—after hours, days, or even weeks. RL mimics how traders think and act in such situations by:
-
Learning from experience instead of fixed rules.
-
Balancing exploration and exploitation—testing new strategies while maximizing known profitable ones.
-
Adapting dynamically to evolving markets.
-
Simulating reward-driven behavior, just like professional traders focus on risk-adjusted returns over time.
This makes RL one of the most promising approaches for algorithmic and quantitative trading.
What You’ll Learn in This Course
By the end of the course, you’ll be able to design, backtest, and implement RL strategies tailored for financial markets.
Core learning outcomes include:
-
Understanding the need for reinforcement learning in trading and the delayed reward challenge.
-
Defining states, actions, policies, rewards, and Q-learning.
-
Exploring Double Q-learning and Experience Replay for better model stability.
-
Managing the exploration vs. exploitation tradeoff effectively.
-
Creating, training, and backtesting RL models on market data.
-
Analyzing returns, risk, Sharpe ratios, and maximum drawdowns.
-
Deploying strategies for paper trading and live trading.
-
Tackling real-world challenges of live execution and their solutions.
Skills You’ll Gain
This course integrates finance, math, machine learning, and programming into a practical RL framework.
-
Finance & Risk Analysis: Sharpe ratio, returns, drawdowns, performance measures.
-
Math & Optimization: Mean squared error, stochastic gradient descent.
-
Python for Trading: Pandas, NumPy, TA-lib, Matplotlib, TensorFlow, Keras.
-
Reinforcement Learning Concepts:
-
States, actions, policies, and rewards.
-
Q-learning and Double Q-learning.
-
Experience Replay.
-
Neural networks for decision-making.
-
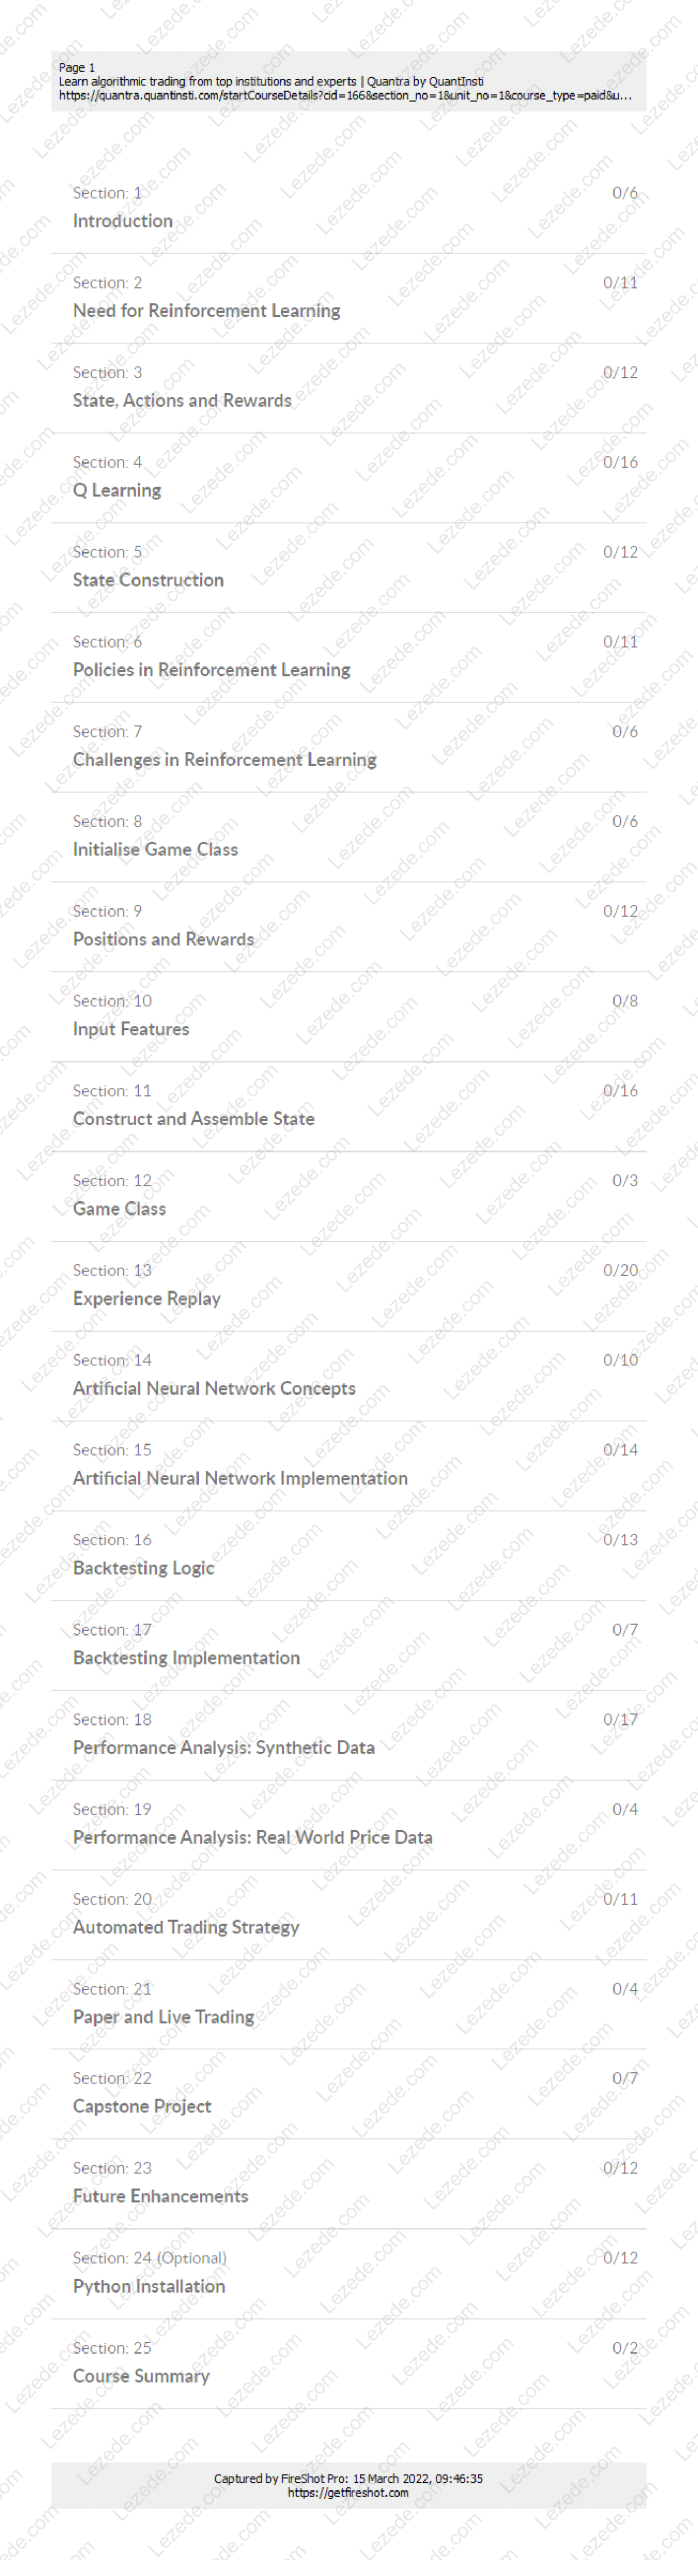
Course Syllabus Snapshot
-
Introduction & Motivation – Why RL matters for trading.
-
Core RL Concepts – States, actions, rewards, policies, and Q-learning.
-
Advanced Methods – Double Q-learning, experience replay, ANN implementation.
-
Backtesting Logic – On synthetic data and real-world financial datasets.
-
Performance Analysis – Returns, Sharpe ratio, drawdowns.
-
Strategy Automation – Building a game class, constructing states, feature engineering.
-
Deployment – Paper and live trading with real market data.
-
Capstone Project – Apply everything to build and test your RL trading model.
-
Future Enhancements – Improving scalability and robustness in live trading.
Course Features
-
Interactive coding practice – Hands-on exercises to strengthen concepts.
-
Capstone project – Build and test a trading system using real market data.
-
Live and paper trading deployment – Bridge the gap between theory and execution.
-
Practical focus – Learn directly from a quant practitioner with real hedge fund experience.
Who Is This Course For?
This course is designed for:
-
Quantitative traders looking to expand into AI-driven strategies.
-
Machine learning practitioners eager to apply RL in finance.
-
Algorithmic traders seeking more adaptive models.
-
Programmers & data scientists who want to bridge coding with trading.
Prerequisites:
-
Basic understanding of financial markets (buying/selling securities).
-
Familiarity with Python libraries (Pandas, Matplotlib, Keras).
-
Some background in machine learning (covered in prerequisite courses like Introduction to Machine Learning for Trading).
About the Instructor – Dr. Thomas Starke
Dr. Thomas Starke holds a Ph.D. in Physics and currently serves as the CEO of AAQuants, a leading proprietary trading firm in Australia. His career highlights include:
-
Senior research fellow at Oxford University.
-
Former roles at Vivienne Court Trading and Memjet Australia.
-
Strategic research leadership for Rolls-Royce Plc (UK).
-
Co-founder of a microchip design company.
With deep expertise in quantitative finance, machine learning, and algorithmic trading, Dr. Starke is uniquely positioned to guide learners through the complexities of RL in trading.
Why Choose Quantra®?
-
Learn faster – Courses designed for applied learning.
-
Practitioner-led teaching – Insights from industry experts.
-
Self-paced learning – Study anywhere, anytime.
-
Practical resources – Access to data, codes, and strategy templates.
Final Thoughts
Reinforcement learning is not just another academic exercise—it’s a game-changing approach to trading that mimics real decision-making under uncertainty. With Deep Reinforcement Learning in Trading by Dr. Thomas Starke, you’ll learn how to design, backtest, and deploy adaptive models that can handle the complexities of modern markets.
If you’re serious about taking your algorithmic trading to the next level, mastering RL is one of the most valuable skills you can acquire today.